While investors debate whether AI spending is running too far ahead of returns, TSMC’s latest results show customers are still buying advanced chips at a rapid pace.
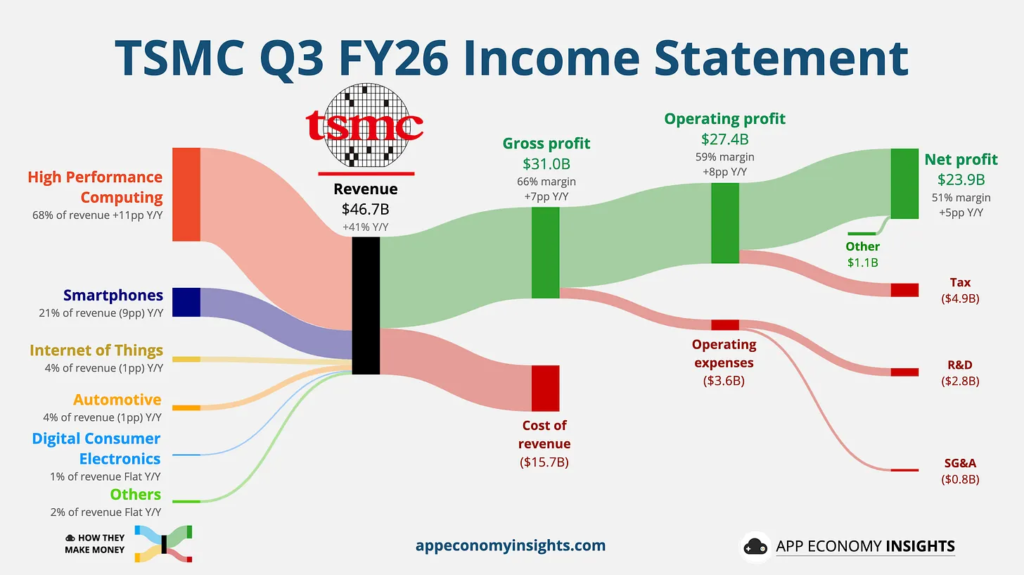
The world’s largest contract chipmaker reported NT$763.1 billion in third-quarter net profit, up approximately 69% from a year earlier. Revenue reached NT$1.49 trillion, or $46.72 billion, exceeding its previous guidance.
Strong sales translate into substantial profits
According to TSMC’s October 15 earnings release, the company delivered:
- Revenue: $46.72 billion.
- Earnings per American depositary share: $4.60.
- Gross margin: 66.4%.
- Operating margin: 58.7%.
- Net profit margin: 51.1%.
Those margins show that TSMC is capturing substantial earnings from the semiconductor expansion.
However, growth brings costs. Gross margin declined from 67.7% in the previous quarter, partly reflecting the initial expense of ramping up its newest manufacturing technology.
The next quarter looks bigger
TSMC expects fourth-quarter revenue of $52.3 billion to $54.3 billion. At the midpoint, that would represent roughly 14% growth from the third quarter.
Its outlook calls for a 65%–67% gross margin and a 56%–58% operating margin.
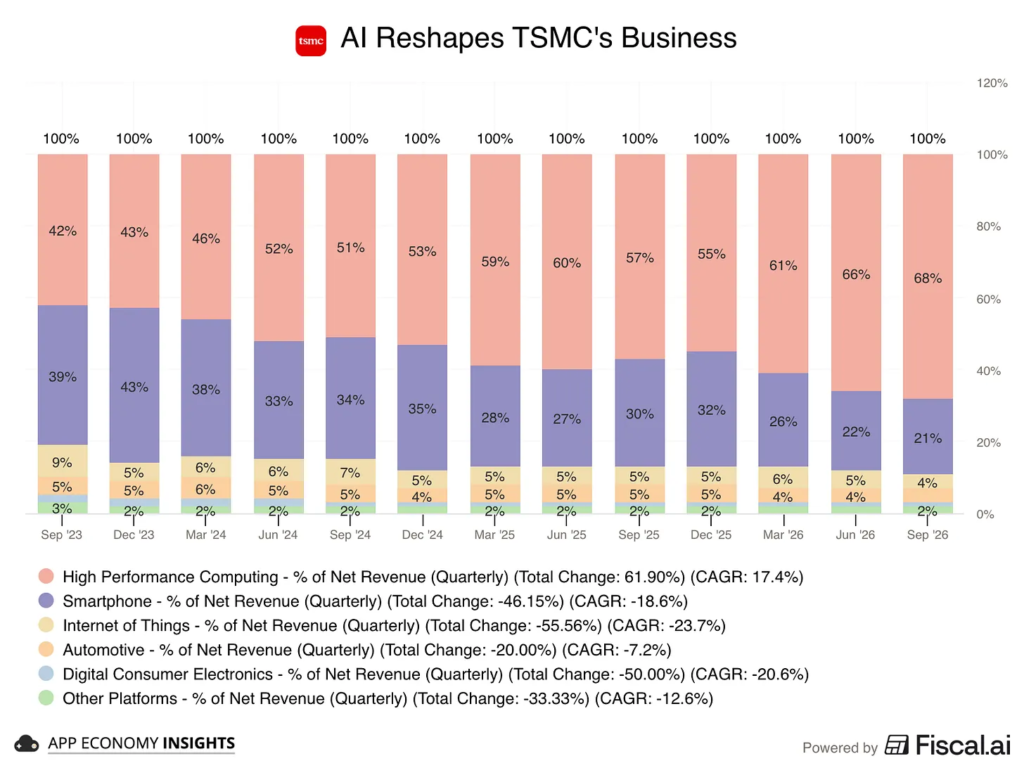
The company’s earnings-call transcript also shows its 2-nanometre technology contributed 8% of wafer revenue, alongside 33% from 3-nanometre chips.
Chip demand and AI returns are different questions
TSMC’s performance demonstrates strong demand for manufacturing capacity. It does not establish that every customer financing AI infrastructure will earn an attractive return.
Related: The AI Boom Is Increasingly Being Financed by Debt.
For now, TSMC is turning demand into real profits. The wider industry still has to prove that the services running on those chips can justify the investment.
Disclosure: This article does not represent investment advice. The content is for informational and educational purposes only.